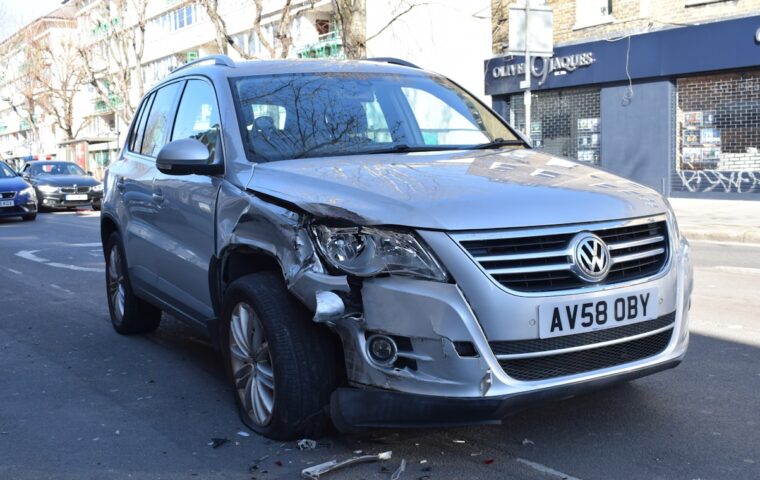
A friend called me a few years back, furious. Her car had been totaled in a parking lot accident that was not her fault, and her insurer cut her a check for $14,000. Sounds fine, until you learn she still owed $19,500 on the loan. She was on the hook for the $5,500 difference on a car she no longer owned. The kicker? She could have closed that gap for about $4 a month and never did, because nobody explained it and she never asked.
I spent years on the broker side of the desk, and most insurance mistakes are not dramatic. They are quiet. They cost you a little every month, or a lot exactly once, on the worst day of your year. The good news is they are avoidable. Here are the ones I saw constantly, why they drain your wallet, and what to do instead.
Buying on price alone and ignoring the deductible math
Everyone shops the premium. Almost nobody does the deductible math. A $250 deductible feels safer than a $1,000 one, so people pay extra for the lower number without checking whether it makes sense.
Run it out. Say dropping your auto or home deductible from $1,000 to $250 costs an extra $180 a year. That $750 of saved out-of-pocket only matters if you file a claim, and you might go five or ten years without one. Worse, filing a small claim can bump your premium at renewal, so the lower deductible quietly nudges you toward claims you should have paid yourself.
Pick the highest deductible you could cover from savings tomorrow without flinching. If you have $1,000 in an emergency fund, a $1,000 deductible usually beats a $250 one over time. Then leave that cushion alone so it is there when you need it.
Skipping gap coverage on a financed car
This is the mistake that got my friend. New cars lose value fast, often 20 percent or more the moment you drive off the lot. Finance with a small down payment and you can owe more than the car is worth for the first couple of years. Standard collision and comprehensive coverage only pays the car's current market value, not the loan balance.
That difference is exactly what gap insurance covers. For a few dollars a month it pays the spread between what you owe and what the car was worth at the time of a total loss. If you put little down, rolled negative equity into the new loan, or took a long 72-month term, you are the person this exists for. I wrote a fuller breakdown of what gap insurance is and when it saves you, but the short version is simple: if a total loss would leave you owing money on a car you no longer have, you probably want it. Just skip the dealer's marked-up flat fee, since your own insurer often adds it for a dollar or two a month.
Underinsuring your home to shave the premium
Home insurance is where people quietly set themselves up for disaster. To lower the premium, some insure the house for what they paid or what it would sell for. But your policy needs to cover the cost to rebuild, a different and usually higher number after a few years of rising construction and labor costs.
Here is the trap. Many policies include a coinsurance clause requiring you to insure to at least 80 percent of replacement cost. Fall below that and the insurer can reduce even a partial claim proportionally. Picture a $40,000 kitchen fire on a house you underinsured. Your payout could be cut by thousands because you carried too little coverage on the whole structure.
Look at your dwelling coverage limit, not your home's market value. Ask your agent for a current replacement-cost estimate every couple of years, and add an inflation-guard or extended-replacement-cost endorsement if your policy offers one. Land value is not part of a rebuild, so do not let the sale price push you into over-insuring either.
Treating health plan choices as a coin flip
Open enrollment rolls around and people pick whatever they had last year, or grab the lowest premium without reading the rest. Both moves cost money. A low-premium, high-deductible plan can be a great deal if you are healthy and pair it with a Health Savings Account, since HSA contributions are tax-advantaged and the money rolls over and stays yours. That same plan can wreck your budget if you have a chronic condition and hit the deductible every January.
The fix is to estimate your real usage. Add up last year's doctor visits, prescriptions, and planned procedures, then compare total annual cost across plans: premium plus expected out-of-pocket, not premium alone. Confirm your doctors are in network and your drugs are on the formulary, because one out-of-network surprise can erase the premium savings.
Confusing life insurance with an investment
An agent paid on commission sells you whole life, calls it "permanent coverage with a savings component," and you sign up paying $300 a month for a policy a fraction the size of what your family needs. I saw this one a lot, and it frustrated me every time.
For most people raising a family or carrying a mortgage, plain term life does the job. It is cheap, simple, and it covers the years when people depend on your income. A healthy person in their thirties can often get a 20-year, $500,000 term policy for $25 to $40 a month. The same coverage in whole life might run ten times that. Whole life does build cash value, but the returns are usually modest and the fees are steep. If you want coverage, buy term. If you want to invest, do it separately in low-cost index funds inside a 401(k), IRA, or HSA, where the expense ratios work for you instead of against you.
Permanent life insurance has a place for a narrow set of needs, like certain estate-planning situations or providing for a dependent with lifelong care needs. That is a conversation for a fee-only financial advisor, not a default everyone should buy.
Letting policies run on autopilot and overpaying for it
Loyalty is not rewarded in insurance the way people assume. Insurers know customers who never shop around will tolerate steady increases, and premiums often creep up at renewal even when nothing about your risk has changed. Your rate is built from dozens of factors, and understanding how insurers decide what you pay makes it obvious why the same coverage can vary by hundreds of dollars between companies.
Shop your auto and home coverage every two or three years, and bundle them if it lowers the combined cost. Report changes that should reduce your rate too, like a teen driver moving out, a shorter commute, or a new alarm system. In most states credit-based insurance scores affect what you pay, so an improved credit profile can help as well.
| Mistake | Roughly what it costs | The fix |
|---|---|---|
| Deductible too low | $100-$200 a year in extra premium | Raise it to match your emergency fund |
| No gap coverage on a financed car | Thousands after a total loss | Add it for a few dollars a month |
| Underinsured home | A reduced claim payout when you need it | Insure to replacement cost, not market value |
| Never re-shopping | Hundreds a year in creep | Compare quotes every 2-3 years |
Fumbling the money side when a claim or payout finally lands
When a claim pays out, or when you fund a big premium, the money mechanics matter more than people think. Paying a hefty annual premium by credit card can trigger a processing fee, while an electronic transfer usually does not. If you are sending a large sum, knowing the difference between wire and ACH transfers and which to use and when can save you a wire fee of $25 to $50 and protect you, since wires are hard to reverse if something looks off.
One more habit: do not let a settlement sit idle in a low-interest checking account. Park it somewhere FDIC-insured that pays interest, and keep balances within the FDIC limit of $250,000 per depositor, per bank, per ownership category. That is a US-specific rule, and it is free money to follow it.
How high should I set my insurance deductible?
A useful starting point is the highest amount you could comfortably pay out of pocket tomorrow without borrowing. If you keep $1,000 in an emergency fund, a $1,000 deductible usually saves you more in premiums over time than a lower one costs you. The right number still depends on your savings, your risk tolerance, and how often you actually file claims.
Is whole life insurance ever worth it?
For most families the answer is no, and term life plus separate investing covers the need at far lower cost. Permanent policies can make sense for specific situations like estate planning or providing for a dependent with lifelong needs. Because the fees and tradeoffs are significant, it is worth reviewing with a fee-only financial advisor rather than buying it as a default.
How often should I shop around for insurance?
Every two or three years is a reasonable cadence, and also after any major life change such as moving, buying a car, marrying, or adding a driver. Premiums tend to creep up at renewal regardless of your actual risk, so comparing a few quotes keeps your insurer honest. Bundling auto and home with one company can lower the combined cost, but only if the bundled price actually beats separate policies.
None of this requires becoming an insurance expert. It mostly takes reading your declarations page once a year, asking a couple of pointed questions, and matching coverage to your real life instead of a salesperson's script. The right answers depend on your own situation, so for the big decisions a licensed agent or a fee-only advisor is worth the conversation. Catch these mistakes early and you keep money that would otherwise leak away, one quiet renewal at a time.