A reader once got turned down for a car loan she should have walked into easily. Good income, low balances, years of on-time payments. The finance manager slid a printout across the desk: a $4,200 collection account she had never heard of, tied to a medical bill belonging to someone with a similar name in another state. That one error was dragging her score down by about 80 points and costing her thousands.
Here is the part that makes me a little angry. Errors on credit reports are common, and the system that creates them is automated while the one that fixes them is slow and manual. Nobody fixes it for you. You have to find the mistake, prove it, and push it through. The good news: it is free, spelled out in federal law, and a normal person can do it. Here is how.
Pull all three reports and read them line by line
You have three credit reports, not one. Equifax, Experian, and TransUnion each keep their own file, and a lender might report to one, two, or all three. An error can sit on a single report and quietly tank one score while the other two look fine. Pull all three free from AnnualCreditReport.com, the site mandated under the Fair Credit Reporting Act; as of 2026 you can pull them weekly at no cost. Do not pay a "score" site. You want the actual reports, not a dashboard.
Then read every line: name spellings, addresses, every open and closed account, the balances, the payment grid, and the hard inquiries. The most common errors:
- An account that is not yours (mixed file, identity theft, or clerical mismatch).
- A payment marked 30 or 60 days late that you actually paid on time.
- A wrong balance or credit limit, throwing off your utilization.
- A paid or settled debt still showing a balance owed.
- The same debt listed twice (a collection plus the original).
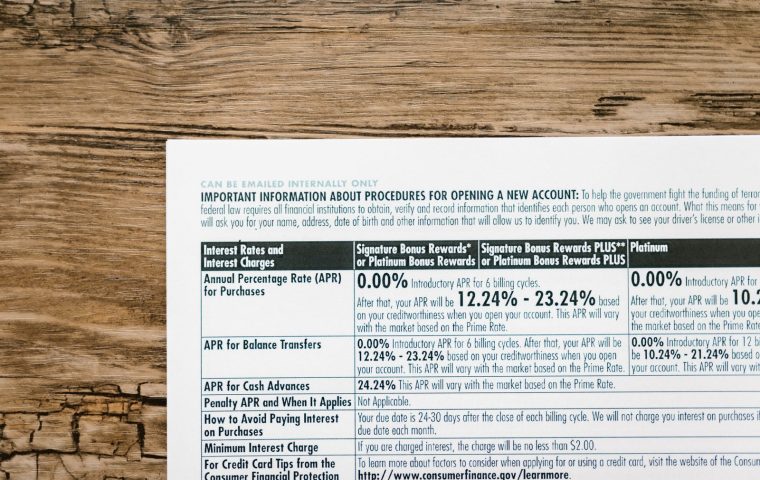
A wrong credit limit is sneaky. If a card with a $10,000 limit is reported as $1,000 and you carry a $900 balance, your utilization reads as 90 percent instead of 9 percent. Fixing that one number can move a score meaningfully, since utilization is one of the heaviest factors. For how balances and interest interact, see How Credit Card Interest and APR Really Work.
Decide what is actually an error worth disputing
Not everything you dislike is an error. A late payment that really was late is accurate, and accurate negative information legally stays for up to seven years (ten for most bankruptcies). Disputing true information as false does not work. What you can dispute is anything inaccurate, incomplete, or unverifiable: wrong dates, wrong amounts, accounts that are not yours, and old debts that should have aged off. For each, write in one plain sentence what is wrong and what is correct. A vague dispute gets a vague brush-off.
Gather your proof before you file
The bureau must investigate, but you give yourself a far better shot if you hand them evidence, not just an assertion. Gather what supports you:
- Bank or card statements showing an on-time payment.
- A payoff letter or "paid in full" confirmation from the creditor.
- A settlement agreement, if you settled.
- For an account that is not yours, anything proving it belongs to someone else.
Keep copies, never originals, and note the dates of what you send and receive. That paper trail is your strongest asset.
File the dispute with the credit bureau
File with each bureau that shows the error; if it appears on two reports, dispute it with both. Three ways:
- Online through each bureau's dispute portal. Fastest, and you can usually upload documents.
- By mail, certified with return receipt. Slower, but it gives dated proof of what you sent. For a serious error or a likely fight, I lean toward mail.
- By phone, which I avoid because there is no written record.
Whichever way you go, state the item, say plainly what is wrong and what is correct, and attach your proof. Under the Fair Credit Reporting Act, the bureau generally has 30 days (sometimes 45) to respond. It contacts the creditor or "furnisher" who reported the item, that company checks its records, and the bureau reports back.
You can also dispute directly with the furnisher, the bank or collector that reported the bad data. Doing both closes the loop, and if the furnisher admits the error in writing, that letter helps if the bureau drags its feet.
Read the result and escalate if they get it wrong
After the investigation, the bureau sends the outcome and a free updated report if anything changed. Three things can happen. They fix it. They mark the item "verified," meaning the furnisher confirmed it. Or they delete it because the furnisher could not verify it in time, which also gets it off the report.
If they "verify" something you know is wrong, do not give up; that first round is often automated and shallow. Next moves:
- Refile with stronger documentation and a written explanation of why the verification was wrong.
- Add a brief consumer statement noting the dispute, so anyone reading the report sees it.
- File a complaint with the Consumer Financial Protection Bureau at consumerfinance.gov. Bureaus take CFPB complaints seriously, and you often get a real response.
If an error is blocking a mortgage already in motion, ask your lender about a "rapid rescore." The lender requests it with your documentation, and updates can post in days instead of weeks. You cannot order it yourself, and it costs a fee, so it is for urgent cases only.
Protect the gain and rebuild from here
Once the error is gone, the score bump is not always instant, but it usually shows up within a cycle or two as the bureaus refresh. From there, the fundamentals hold the line: pay on time, keep utilization low, and do not close your oldest card.
If part of what hurt you was real debt, not just an error, that is a different project. A balance at 24 percent APR bleeds you every month, and moving it can buy breathing room, though it has traps. I weighed that math in Balance Transfer Cards: Smart Move or Trap. And if the deeper problem is spending leaking out in amounts you never notice, the exercise that reset my own habits is in What a No-Spend Month Taught Me About My Habits.
One honest caveat. This explains how the process works in general so you can act on your own situation; the right move depends on your facts, your state, and the kind of error. If you are facing identity theft, a debt heading toward a lawsuit, or anything tangled, a nonprofit credit counselor or a consumer-rights attorney is worth a conversation, and many offer a free consult.
Does disputing an error hurt my credit score?
No. Filing a dispute does not lower your score, and there is no penalty for being wrong. The only thing that changes your score is the outcome: if a bad mark is removed, it can go up. Pulling your own reports is a soft inquiry, so it never costs points.
How long does it take to fix an error on my credit report?
The bureau generally has 30 days (up to 45 in some cases) to investigate and respond. Simple errors with clear proof can resolve faster. If they wrongly verify the item, expect to file again, so a contested error can take a couple of months.
Should I pay a credit repair company to dispute errors for me?
Usually not. A credit repair company cannot do anything you cannot do yourself for free, and it cannot legally remove accurate negative information no matter what it promises. By law it also cannot charge you before performing services. For genuine errors, do it yourself.
Fixing a credit report is unglamorous work: pull the files, find the wrong line, prove it, and push until it sticks. But the payoff is real, because that one corrected number can change the rate on the next big thing you borrow for. Keep your paperwork, and do not let a "verified" letter be the end of the story when you know you are right.